Home Loan Balance Transfer: Lower EMI vs Lower Tenure?
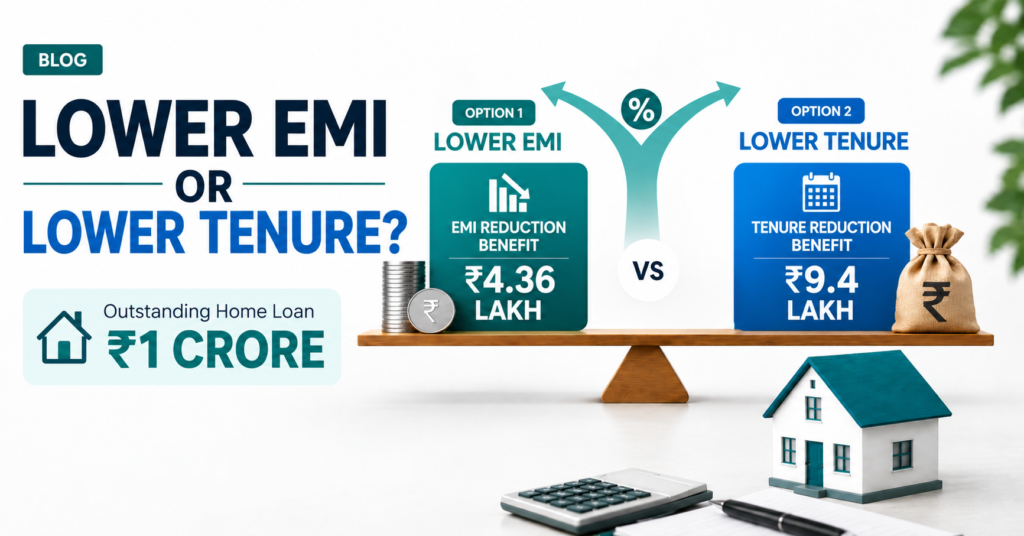
A home loan balance transfer to a lower interest rate can help reduce your overall borrowing cost. Transferring your home loan at a lower interest rate can reduce your EMI or tenure. Understand which option may save more and which could suit your financial goals.
A lower home loan interest rate sounds straightforward: pay less interest and save money. But when you transfer an existing home loan to a lower rate, there is another decision to make. What should you do with the benefit of that lower rate? You could reduce your EMI and improve your monthly cash flow. Or you could continue paying approximately the same EMI and potentially repay the loan earlier. Both approaches have advantages. But they can produce very different financial outcomes.
Illustrative Home Loan Balance Transfer Example
Consider a borrower with:
| Particular | Illustration |
|---|---|
| Outstanding home loan | ₹1 crore |
| Existing rate | 7.40% p.a. |
| Remaining tenure | 240 months |
| Existing EMI | ~₹79,949 |
| Illustrative new rate | 7.10% p.a. |
At the existing rate and tenure, the borrower would pay approximately ₹1.92 crore over the remaining 20 years, including principal and interest. Now, let’s see what could happen after home loan balance transfer to the illustrative lower rate of 7.10%. When considering a home loan balance transfer, borrowers broadly have two choices.
Option 1: Reduce the EMI
If the borrower transfers the loan at 7.10% and retains the original remaining tenure of 240 months, the EMI could reduce from approximately ₹79,949 to ₹78,131. That is a reduction of around ₹1,818 per month.
Over the remaining tenure, the lower interest rate could reduce the borrower’s total outflow by approximately ₹4.36 lakh.
For someone who wants more flexibility in the monthly household budget, this can be valuable. But, there is another way to use the lower interest rate.
Option 2: Keep the EMI similar and reduce the tenure
Instead of taking the benefit as a lower EMI, the borrower could continue paying approximately the existing EMI of ₹79,949.
Because the interest rate is now lower, a greater portion of the EMI goes towards repaying the principal. As a result, the loan could potentially be repaid earlier. And this is where the long-term impact becomes more meaningful.
*In this illustration, retaining approximately the same EMI and reducing the tenure could result in total savings of around ₹9.4 lakh compared with continuing the existing loan.
That is close to ₹10 lakh of potential savings on a ₹1 crore outstanding home loan — simply by using the benefit of the lower rate differently.
The difference at a glance
| Scenario | What changes? | Approximate benefit |
|---|---|---|
| Continue existing loan | No change | — |
| Transfer + lower EMI | EMI reduces by ~₹1,818/month | ~₹4.36 lakh total saving |
| Transfer + retain similar EMI | Loan tenure reduces | ~₹9.4 lakh total saving |
| Additional benefit of tenure reduction | Compared with lower-EMI option | ~₹5.08 lakh additional saving |
Or, look at it from another angle:
| Scenario | EMI | Approx. tenure | Approx. lifetime benefit |
|---|---|---|---|
| Existing loan | ₹79,949 | 240 months | — |
| Transfer + lower EMI | ₹78,131 | 240 months | ~₹4.36 lakh |
| Transfer + retain similar EMI | ₹79,949 | 228 months | ~₹9.4 lakh |
This is why a home loan balance transfer should not be evaluated only on the basis of the new interest rate.
See what this could look like for your own home loan
Enter your actual outstanding loan amount, current interest rate, remaining tenure and an indicative transfer rate. The calculator will show both possibilities side by side — a lower EMI and a potentially shorter tenure.
Calculate My Balance Transfer Benefit
How you use the benefit of that lower rate can matter just as much.
So should everyone reduce tenure?
Not necessarily.
A lower EMI may be more appropriate if you want to improve monthly cash flow — for example, because of higher household expenses, education costs, other financial commitments or the need to build an emergency fund.
On the other hand, if your current EMI is comfortable, your cash flow is stable and you have adequate emergency savings, retaining approximately the same EMI could help you repay the loan sooner and potentially save more interest over the remaining tenure.
The right choice depends on your financial situation and priorities.
Before transferring, compare these numbers
Before proceeding with a home loan balance transfer, don’t compare interest rates alone. Look at the complete financial picture, including:
- Current outstanding principal
- Existing interest rate and EMI
- Remaining loan tenure
- New interest rate
- EMI at the new rate
- Revised tenure if you retain approximately the same EMI
- Total remaining interest under each option
For a long-tenure loan, even a relatively small difference in the interest rate can have a meaningful impact over time. But the real benefit becomes clearer only when you compare the total remaining cost of the loan, not just the monthly EMI. A home loan transfer shouldn’t simply answer: “Can I get a lower interest rate?”. It should also answer: “How can I use the lower rate most effectively for my financial goals?”
Not sure whether a lower EMI or shorter tenure would work better for your home loan? Monest Solutions can help you compare the numbers across available options—including EMI, tenure, estimated interest outflow and applicable transfer costs—before you decide.
Expert Advice. Personalized Service.
Call / WhatsApp: +91 99589 91429 / Send an enquiry
Frequently Asked Questions
Is it better to reduce EMI or tenure after a home loan balance transfer?
It depends on your financial priorities. A lower EMI can improve monthly cash flow, while retaining a similar EMI after transferring to a lower rate may help reduce the loan tenure and total interest outflow.
Does a home loan balance transfer reduce the loan tenure?
Not automatically. If you transfer to a lower interest rate and continue paying approximately the same EMI, the lower interest burden may allow the loan to be repaid sooner, subject to the lender’s terms and repayment schedule.
When is a home loan balance transfer worth considering?
It may be worth evaluating when the potential savings from the lower rate exceed processing fees. The remaining tenure and outstanding principal also influence the potential benefit.
All calculations are illustrative. Actual interest rates, EMI, tenure, savings and eligibility depend on lender policies, borrower profile, outstanding loan details, applicable charges and other terms.
For borrowers who want to understand the broader regulatory framework governing housing finance companies, the Reserve Bank of India publishes its Housing Finance Companies Directions covering various aspects of housing finance and lending practices.